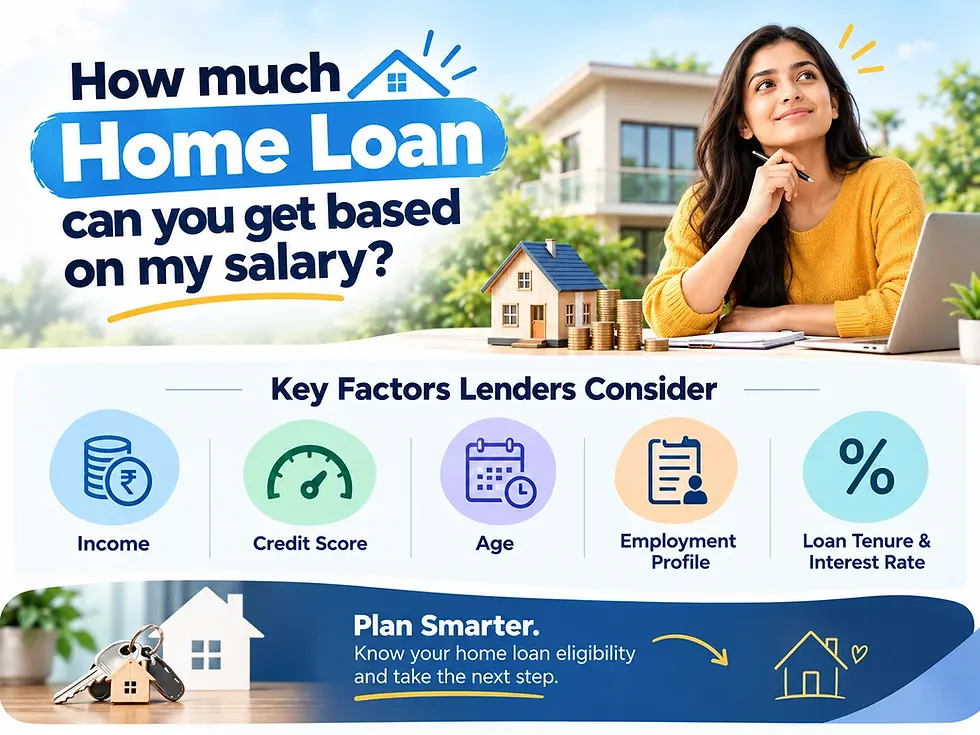
How much Home Loan can you get based on my salary?

Purchasing a house is one of the most important financial decisions you will make, and estimating how much you can borrow is a crucial step in buying a house. Although your preference for houses and your savings matter greatly, your income is one of the main determinants of online home loan eligibility. Undoubtedly, one of the first things that comes to mind while planning to purchase a house is: How much home loan will I be able to get based on my salary?
Your monthly income indicates your ability to repay and helps lenders estimate what proportion of your EMI you can afford. Along with your salary, lenders also consider your current EMIs, other financial responsibilities, credit score, age, job profile, loan tenure, interest rate, and any other sources of income. A longer repayment tenure can increase your eligible loan amount by lowering your monthly EMI.
With the help of a home loan eligibility calculator, the process is made easier, as you can get an estimate of the loan amount that you are eligible for. Just put in your income details, financial obligations, desired tenure of the loan, and other requested details; you will be able to get a fair idea of how much you can actually borrow from the lender.
So, how much instant home loan can one acquire based on their salary? Is there a formula to calculate the loan amount based on salary, and what else affects eligibility? In this blog, we will look at the various factors lenders consider when deciding an individual's home loan eligibility.
The 50-30-20 Rule for Budgeting Your Home Loan Requirements
Lenders have their own qualifying criteria to decide the home loan amount you're eligible for; the 50-30-20 rule can help with planning. The rule divides your net monthly income into 3 broad heads: necessities, desires, and savings & investment.
50% towards Needs
Around 50% of your monthly income can go towards essential expenses (including your home loan EMI)
Food
Clothing
Rent
Healthcare
Insurance
Home Loan EMI
30% towards Wants
About 30% of your monthly income goes to wants and miscellaneous spending.
Hobbies
Entertainment
Travel
Dining Out
20% towards Savings & Investments
The other 20% can go towards savings and investments. This part of your income will enable you to have financial security in preparation for the future, including the following:
Emergencies
Long-term goals
Short-term goals
Retirement planning
Investments
Home Loan Eligibility
Salaried Applicant
For salaried applicants, the bank checks parameters such as monthly income, employment stability, work experience, credit score, and other financial liabilities to assess repayment ability.
Self-Employed Applicant
For self-employed applicants, lenders may consider factors such as business sustainability, income stability, tax documents, financial records, banking activities, and financial performance when assessing eligibility.
Age Requirements
Age is another crucial factor lenders consider when deciding home loan eligibility. Applicants should meet the lender's minimum age criteria, and there may be an upper age limit at loan maturity. These age requirements may vary by lender.
FOIR (Fixed Obligations to Income Ratio)
It refers to the percentage of your monthly income already obligated to paying your existing financial liabilities, such as loan EMIs and credit card dues. The FOIR should be moderate enough to ensure repayment capability.
How You Can Calculate Your Loan Amount Eligibility
Multiplier Method
The multiplier approach offers a simplified way to calculate your home loan eligibility using a multiplier based on your income. The multiplier value depends on several factors, including your income, age, loan tenure, interest rates, and obligations.
Net Monthly Income (After tax deductions) = ₹55,000
Additional Income = ₹5,000
Existing EMI = ₹4,000
Loan Tenure = 20 Years
Interest Rate = 8.50 % per annum
Calculation:
Step 1: Total Income = Net Monthly Income + Additional Income
= ₹55,000 + ₹5,000= ₹60,000
Step 2: Deduct existing EMI = ₹60,000 - ₹4,000 = ₹56,000
Step 3: Apply an illustrative multiplier = 20 (if a lender uses a multiplier of 20 for illustration)
Loan Eligibility = ₹56,000 X 20 = ₹11,20,000
Important to note: This is just an illustration. Your actual home loan eligibility will vary based on other factors, including lenders' eligibility criteria, FOIR, credit profile, age, income stability, obligations, and more.
Document Requirements for Salaried Individuals to Apply for a Home Loan
- Identity Proof
- Address Proof
- Salary Slips
- Bank Statements
- Employment Proof Documents
Conclusion
Knowing how much you can borrow based on your salary will help you plan your purchase more practically. Although your monthly income is a key determinant of your loan repayment capacity, banks also consider other factors, such as EMIs, FOIR, credit rating, age, job security, extra income, loan period, and interest rate.
Before applying for a home loan, analyse your monthly budget and confirm whether the EMIs are reasonable given your expenses and other financial obligations.
Whether you want to apply for a home loan online or if you are exploring different housing loans, help yourself with the Lenditt Loan App.
Frequently Asked Questions
What home loan amount am I eligible for based on my salary?
Home loan eligibility depends on your monthly income and other factors like EMIs, credit rating, age, employment profile, loan period, interest rate, and others.
Will my higher salary make me eligible for a higher home loan?
Yes, a higher salary with steady income can increase your repayment capacity so that you may become eligible for a higher home loan.
What are the factors that determine home loan eligibility?
Lenders consider your income, age, credit score, financial stability, financial commitments, FOIR, loan tenure, interest rate, and other income sources to evaluate your home loan eligibility.
What is FOIR in home loan eligibility?
The term FOIR stands for the Fixed Obligation to Income Ratio. It is the percentage of your monthly income committed to your existing financial obligations, such as loan EMIs and credit card payments.